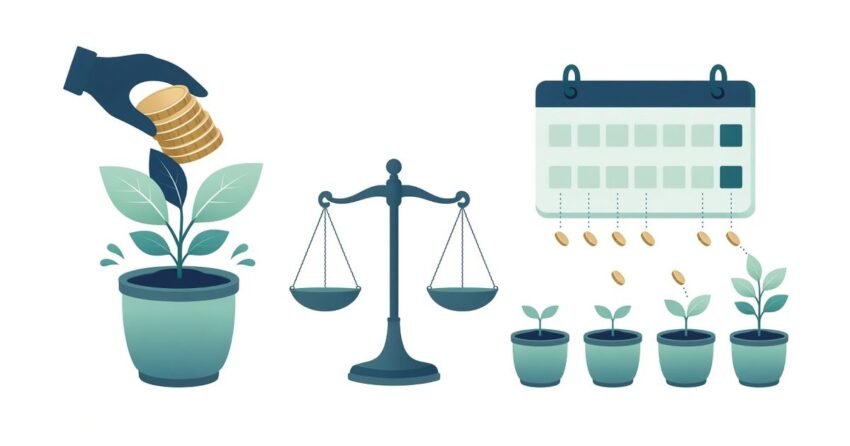
Short answer: Historically, investing a lump sum all at once has beaten dollar-cost averaging (DCA) about two-thirds of the time, because markets have risen more often than they have fallen and cash waiting on the sidelines misses those gains. DCA wins mainly when prices fall soon after you start. It is still a sensible choice if it is the only way you will actually invest, or if a sudden drop would make you panic and sell.
“Should I invest everything now or spread it out?” is one of the most common questions new investors ask, whether they have a bonus, an inheritance, or savings they want to put into an index fund or Bitcoin. Most answers online are opinions. This guide looks at what the research from Vanguard and Morningstar actually found, where DCA genuinely helps, and how the idea applies to a volatile asset like Bitcoin, without any price predictions.
What Are Dollar-Cost Averaging and Lump-Sum Investing?
Lump-sum investing (LS) means putting all the money you have available into the market at once. If you have $10,000 to invest today, you invest $10,000 today.
Dollar-cost averaging (DCA), which Vanguard calls cost averaging, means splitting that same amount into equal parts and investing them on a schedule, for example $2,500 a month for four months. Because you buy at several different prices, no single day decides your average cost.
There is an important distinction that many articles skip. Morningstar’s Paul Kaplan points out that DCA is not the same as systematic investing, which is investing money as you earn it, such as a fixed amount from every paycheck. If you do not have a lump sum, there is no choice to make: investing regularly from income is simply how most people build wealth. The DCA vs lump sum debate only applies when the full amount is already sitting in your account.
What the Research Actually Says
Vanguard: lump sum won roughly two-thirds of the time
Vanguard’s paper “Cost averaging: Invest now or temporarily hold your cash?” compared both approaches across the U.S., U.K., Canada, Europe, Australia, and a global index, using rolling one-year periods from 1976 to 2022. Its main findings:
- Lump-sum investing outperformed cost averaging about 68% of the time in the global index, after one year.
- Across markets, the lump-sum “hit ratio” ranged from 61.6% to 73.7%, and it rose the longer cost averaging took to fully invest the money (Vanguard UK summary).
- At the median, with a three-month cost-averaging plan, lump sum ended with 2.2% more wealth for a 100% stock portfolio, 1.8% for 60/40 stocks/bonds, and 1.2% for 40/60.
- Cost averaging still beat staying entirely in cash about 69% of the time.
Vanguard explains the result simply: over 1976–2022, U.S. stocks beat cash (3-month Treasury bills) 76% of the time and bonds beat cash 68% of the time. Every month money sits in cash waiting to be invested is a month it is not earning that extra return, which Vanguard calls the “opportunity cost of lost risk premium.”
Morningstar: DCA rarely improved returns over long periods
Morningstar reached a similar conclusion. In a 2019 study of an all-equity portfolio going back to 1926, dollar-cost averaging improved returns in 27.8% of 10-month periods but only 10.0% of 10-year periods. Morningstar researchers Maciej Kowara and Paul Kaplan also argued that DCA can make your outcome more uncertain, not less, when risk is measured by the spread of dollar-weighted returns (Morningstar Australia).
In Kaplan’s words, DCA is effectively a bet that the market will drop shortly after you receive your money and recover later. If you cannot predict that, you have no reason to expect DCA to win (interview).
When Dollar-Cost Averaging Does Win
DCA is not useless. It wins in falling markets, and the difference can be large. Morningstar notes that during the technology crash from March 2000 to October 2002, DCA into an all-equity portfolio limited losses to 1.75%, while lump-sum investors suffered an annualized loss of 13.84% (source).
Vanguard’s numbers show the same pattern. In the worst 5% of outcomes, cost averaging finished ahead by 3.6% for an all-stock portfolio. In the best 5%, lump sum led by as much as 6.4%. Vanguard bases its recommendation on the more likely middle range of outcomes, where lump sum came out ahead.
The catch is that you only know you were in a falling market afterward. Choosing DCA because you “feel” a crash is coming is market timing, and it usually does not work.
The Behavioral Case for DCA
Numbers are not everything. Vanguard’s paper says most investors should invest a lump sum immediately, “particularly those without significant aversion to loss.” The flip side is that if putting everything in at once would cause you serious anxiety, and a quick 20% drop would make you sell in a panic, spreading the purchase over a few months can be the better real-world choice. A strategy you stick with beats a “better” strategy you abandon.
Morningstar also notes that a systematic approach can help manage the behavioral barriers that get in the way of reaching your goals. The honest framing: DCA is a tool for managing regret and emotions, not for earning higher returns.
A middle path
If you are torn, Vanguard’s data suggests that a shorter averaging period costs less than a long one, because the lump-sum advantage grew as the cost-averaging period got longer. Investing part now and the rest over a few months is a compromise many investors use. Whatever you choose, set the schedule in advance and automate it.
How DCA Applies to Bitcoin and Crypto
The research above is about stocks and bonds. There is no comparable decades-long study for Bitcoin, which has only existed since 2009, so nobody can tell you with the same confidence which approach “wins” for crypto. What we can say is how the mechanics differ.
Volatility is much higher
The U.S. SEC’s investor alert on Bitcoin notes that its exchange rate has dropped more than 50% in a single day. With swings like that, the timing of a single lump-sum purchase matters more, and the emotional pain of buying right before a sharp drop is bigger. That is exactly the situation where the behavioral argument for DCA is strongest. It does not change the underlying logic, though: if the price rises over your averaging period, DCA will have bought less.
Fees can quietly eat a DCA plan
With small, frequent purchases, fees matter more than timing. A percentage fee takes the same share of every order. A fixed fee per order takes a bigger share of small orders, so four $25 weekly buys can cost far more in fees than one $100 monthly buy. Before setting up a recurring buy, check the trading fee, the funding or card fee, the spread between the quoted price and the market price, and any network fee if you withdraw to your own wallet each time.
Platform risk does not average out
DCA spreads out your price risk, not your platform risk. The SEC warns that crypto platforms may lack the protections of regulated brokers and that assets can be lost if a platform fails, is hacked, or goes bankrupt (Investor.gov). The SEC’s guidance is that the only money to put into a speculative investment is money you can afford to lose entirely.
A simple crypto DCA checklist
- Decide your total crypto allocation first, then divide it into the schedule. DCA should not become “buy forever without a limit.”
- Pick a fixed day (for example, the day after payday) and automate it.
- Compare the real cost per order, not the headline “zero fee.”
- Do not skip buys after a drop or double them after a rally. That turns DCA back into market timing.
- Keep records of every purchase for taxes in your country.
So Which Should You Choose?
- You have a lump sum, a long time horizon, and can tolerate a drop: the evidence favors investing it now.
- You have a lump sum but a crash right after investing would make you sell: a short, pre-set DCA plan (a few months) is a reasonable compromise.
- You invest from your salary: keep investing regularly. That is systematic investing, and it is how most people build wealth.
- It is crypto: the same logic applies, but size the position for a total loss, watch per-order fees, and do not expect any schedule to protect you from a falling market.
Disclaimer: This article is for educational purposes only and is not financial advice. Past performance does not guarantee future results. Crypto assets are highly volatile and you can lose all of your money.
Frequently Asked Questions
Is dollar-cost averaging better than lump-sum investing?
Not on average. Vanguard found lump-sum investing beat cost averaging about 68% of the time over rolling one-year periods from 1976 to 2022. DCA tends to win only when markets fall shortly after you begin.
Does DCA reduce risk?
It reduces the risk of regret from investing everything right before a drop. Morningstar’s research suggests it does not reliably reduce investment risk and can make dollar-weighted returns more uncertain. Your asset mix matters more for risk than your entry schedule.
Should I DCA into Bitcoin?
Many people do, mainly for emotional reasons, because Bitcoin’s price swings are extreme. No long-term study proves it wins for crypto. If you do it, keep fees low, automate the schedule, and only invest money you can afford to lose.
How long should a DCA period be?
Shorter is usually cheaper. Vanguard found the lump-sum advantage grew as the cost-averaging period got longer, so a plan of a few months gives up less expected return than one stretched over years.