Quick answer: In a sharp market sell-off, most long-horizon retirement savers should avoid panic selling, keep contributing if they can, and let a sensible asset allocation do its job. Near-retirees and retirees may still need to rebalance or shore up cash-and-bond reserves—even after stocks have already fallen—so they are not forced to sell equities in a prolonged downturn. Target-date funds automate much of that glide path, but they do not replace a plan for spending needs.
On November 5, 2026, U.S. stocks sold off hard. According to Yahoo Finance’s market coverage, the Nasdaq Composite dropped about 5.5% and closed in correction territory, the S&P 500 fell about 4.3%, and the Dow lost more than 1,800 points (about 3.4%). Tech and semiconductor names led the decline. Days like that raise a practical question for 401(k) and IRA holders: sit tight, rebalance, or make a bigger change?
This article summarizes guidance from certified financial planners and Morningstar’s Christine Benz as reported the same day by Yahoo Finance—not predictions about where markets go next.
First Principle: Focus on What You Can Control
In a November 5, 2026 Yahoo Finance interview, CFP Ryan Haiss of Flynn Zito Capital Management said market fluctuations are a natural part of investing and that clients should remember wealth-building is a long-term process. CFP Justin Smith of Savant Wealth Management put it simply: “Stay calm,” and focus on controllable items such as the retirement plan and cash holdings.
That framing matters because selling after a drop locks in losses and creates a second problem: you still have to decide when to get back in. Missing the recovery often hurts more than the decline that triggered the sale. If you are decades from needing the money, a single ugly session—or even a rough quarter—is usually noise relative to a multi-decade compounding path.
If You Are Young or Mid-Career: Sitting Tight Is Often the Plan
For savers with many years until retirement, the Yahoo Finance experts emphasized continuing automatic contributions. When you invest on a schedule through payroll or IRA transfers, you buy more shares when prices are lower and fewer when prices are higher. That is ordinary systematic investing—not a market-timing stunt.
Practical moves that usually help more than trading the dip: keep automatic contributions, capture any employer match, stop doom-scrolling balances, and review whether your equity percentage still matches your written plan.
If you receive a bonus or have cash you intended to invest, research on lump-sum versus dollar-cost averaging still applies: historically, investing sooner has often beaten spreading purchases out, but spreading can be the better behavioral choice if a full buy would make you panic later. See our breakdown of DCA vs lump sum for the evidence and caveats.
Target-Date Funds: Built-In Rebalancing, Not a Magic Shield
Many workplace plans default savers into target-date funds (for example, a “2050” or “2040” fund). The manager holds a mix of stocks and bonds and gradually shifts toward a more conservative blend as the stated year approaches.
That helps in a sell-off because rebalancing is automatic and new contributions buy the whole mix. It does not eliminate losses when stocks fall, guarantee near-term cash, or customize for a pension or a spouse’s different timeline.
If your only retirement account is a target-date fund and you are years from needing withdrawals, sitting through volatility is often exactly what the product was designed for. If you are within a few years of retirement, still verify the fund’s current stock/bond mix matches how much risk you can take with money you may spend soon.
Near Retirement: “Do Nothing” Is Not Always Best
Christine Benz, Morningstar’s director of personal finance, told Yahoo Finance that the mantra to do nothing when the market drops “isn’t necessarily great advice for people approaching retirement.” Her point: a long bull run can leave portfolios overweight stocks if owners never rebalanced. Even after a decline, it can still be reasonable to lighten equity risk if the portfolio remains more aggressive than the plan calls for.
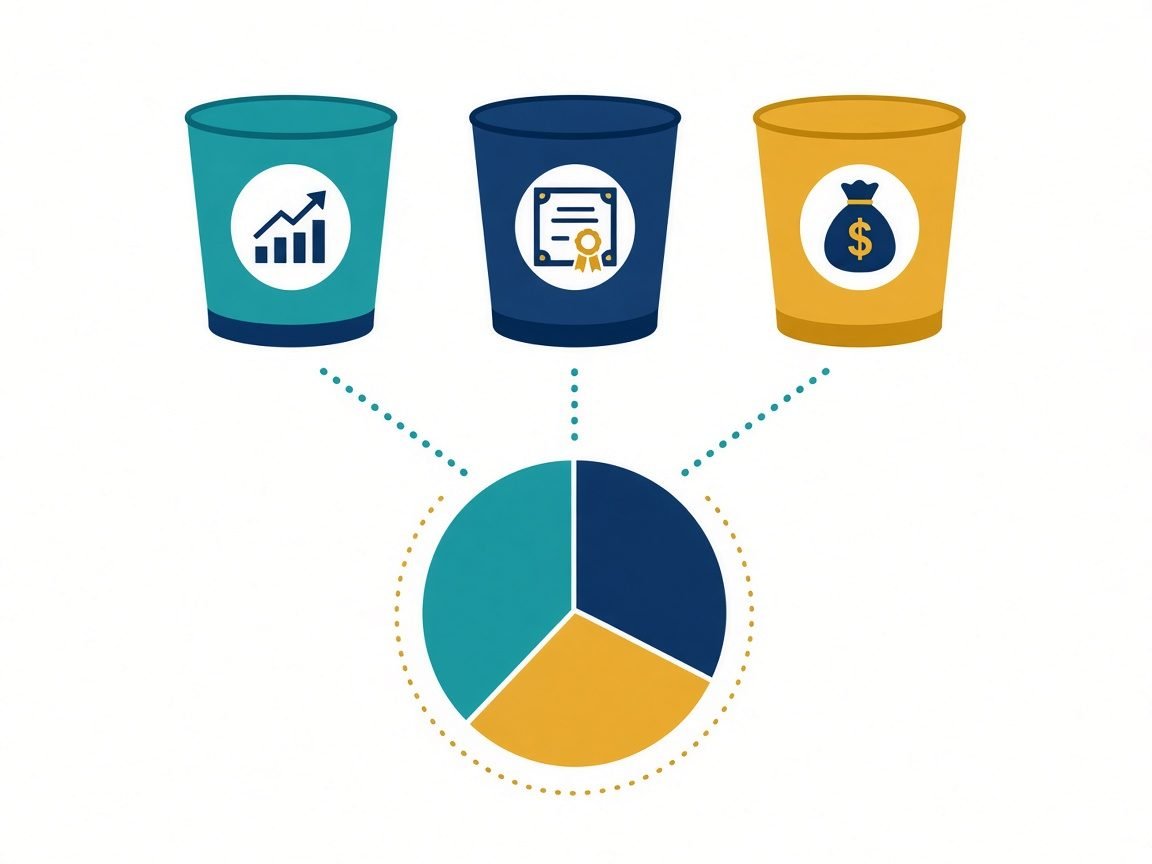
Benz’s concrete suggestion, as reported by Yahoo Finance: pre-retirees and retirees should hold roughly five to 10 years of anticipated portfolio withdrawals in a combination of cash and high-quality bonds. Those safer assets act as a bulwark so you are less likely to sell stocks during a sustained downturn. She also noted that yields on bonds and cash, while lower than their recent peaks amid rate-cut expectations, remained “quite decent” relative to a few years earlier; Yahoo Finance’s article cited some high-yield savings and CD rates still above 4% at the time of publication.
Related reading on cash sleeves: SGOV vs high-yield savings and how much emergency fund you may need.
When Rebalancing Still Makes Sense After a Drop
Rebalancing means restoring your portfolio to target weights—for example, selling what grew too large and buying what shrank, or directing new contributions to the underweight side.
Yahoo Finance noted a common adviser rule of thumb: consider rebalancing when a major asset class drifts about 7% to 10% away from its target. Another rough stock-allocation heuristic mentioned in the same piece is “110 minus your age” for an equity percentage (so a 60-year-old might aim near 50% stocks). Treat heuristics as conversation starters, not laws; risk capacity, pensions, and spending plans matter more than a slogan.
Rebalancing can still be rational after a sell-off when:
- Stocks remain above your written target even after the decline (you never trimmed during the rally).
- You need to fund a cash/bond bucket for planned withdrawals in the next several years.
- Your risk tolerance has permanently changed—and you accept that you may lag in a future rebound.
Rebalancing is usually a poor response when:
- You are selling stocks simply because prices fell and fear feels urgent.
- You abandon a diversified plan for an all-cash bet you cannot time your way back from.
- Trading costs, bid-ask spreads, or tax bills in a taxable account wipe out the benefit (IRAs/401(k)s avoid immediate capital-gains tax on internal trades).
Haiss cautioned that if a decline makes you feel your portfolio is too aggressive, it may still be wise to wait for a recovery before making large changes—unless the allocation was already wrong for your timeline. The distinction is important: correcting a mismatched plan is risk management; reacting to pain alone is market timing.
A Simple Decision Framework by Life Stage
20s–40s, stable job, decades to go
Prioritize contributions and diversification. Use the sell-off as a reminder to automate investing, not as a reason to freeze. Check allocation annually, not daily.
50s to early retirement
Confirm you are not accidentally running a 90%+ stock portfolio after years of growth. Build Benz’s cash-and-bond runway. Stress-test whether another 20%–30% equity drop would force sales for living expenses—sequence-of-returns risk matters more near and in retirement than textbook averages.
What Not to Do
Do not confuse one scary session with a full plan change, raid retirement accounts for non-essentials, treat bonds and cash as “wasted” ballast, or ignore taxes when reshuffling taxable accounts. Sentiment gauges such as the Fear and Greed Index describe crowd mood—they are not buy/sell signals.
A Calm Checklist for the Next Statement Cycle
Write down your target mix and last rebalance date; estimate one year of essential spending and its funding source; check your target-date fund’s actual stock percentage; keep contributing if you can; and schedule a routine fiduciary review so you are not inventing a plan mid-panic (a point Yahoo Finance columnist Kerry Hannon also stresses).
FAQ
Should I move my 401(k) to cash after a big drop?
Usually no, especially if retirement is years away. Moving to cash crystallizes losses and requires a second correct decision about when to re-enter. Near-retirees may raise cash deliberately as part of a written spending plan—not as a fear trade.
Is rebalancing the same as market timing?
No. Rebalancing restores a predetermined mix. Market timing tries to predict short-term moves. Rules based on percentage drift or calendar reviews are rebalancing; “I’ll sell until it feels safe” is timing.
Are target-date funds safe in a crash?
They are diversified and professionally rebalanced, but equity-heavy funds can still fall sharply. “Safe” depends on your horizon and withdrawal needs, not the product label alone.
What if this sell-off makes me realize I took too much risk?
That is useful information. Adjust toward a mix you can hold through future declines, preferably with a written policy and enough cash/bonds for near-term needs. Making the entire change at the bottom of a panic can still be costly—plan the destination, then implement deliberately.
Bottom Line
A 5%-plus Nasdaq day is frightening on a statement and ordinary in market history. Young and mid-career savers generally serve themselves by staying invested and continuing contributions. People near or in retirement should pay more attention to withdrawal reserves and whether stocks still dominate the portfolio after years of gains. Rebalancing can be prudent risk management; panic selling rarely is. Build the plan on quiet days so you are not inventing one during a sell-off.
Not financial advice. This article is educational only and is not a recommendation to buy, sell, or hold any security. Market conditions change. Consider your own time horizon, tax situation, and, if needed, advice from a qualified fiduciary professional.