
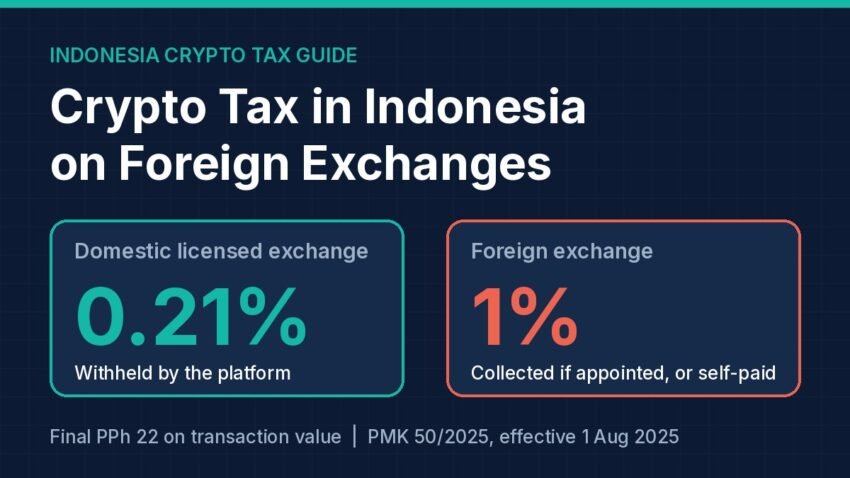
Short answer: Since 1 August 2025, Indonesia taxes crypto sales with a final income tax (PPh Pasal 22) of 0.21% of the transaction value when you trade on a domestic, OJK-licensed platform, and 1% when you trade on a foreign exchange. Domestic platforms withhold the 0.21% for you. On a foreign exchange, the platform collects the 1% only if the tax office (DJP) has appointed it; otherwise you must pay and report it yourself. Buying crypto no longer carries VAT.
Those rules come from Finance Minister Regulation (PMK) No. 50 of 2025, still listed as active by the DJP in November 2026. This general explainer (not tax advice) shows why your choice of platform matters.
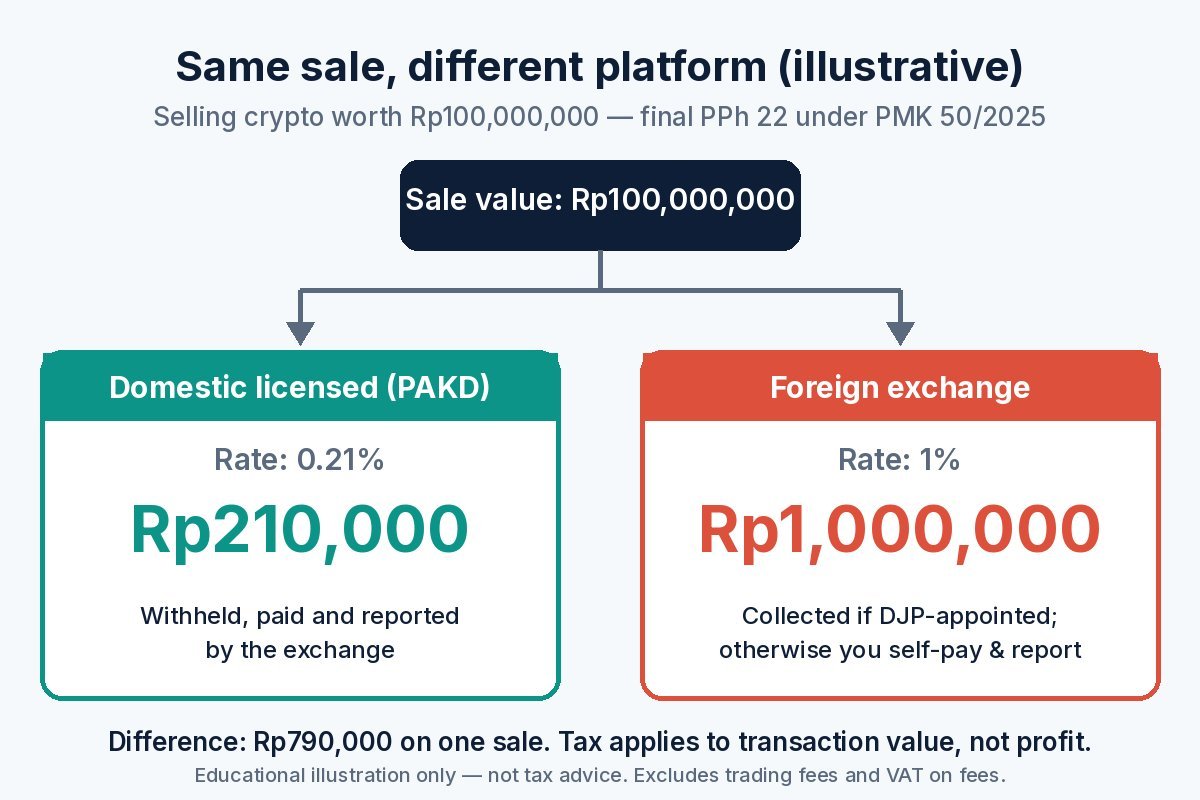
Same sale, different platform: 0.21% final PPh 22 on a domestic licensed exchange vs 1% on a foreign exchange (illustrative).
The Current Rules at a Glance
According to the DJP press release of 31 July 2025, PMK 50/2025 was signed on 25 July 2025 and took effect on 1 August 2025. The main changes:
| Item | Before (PMK 81/2024 rules) | Now (PMK 50/2025) |
|---|---|---|
| Selling crypto, domestic platform | 0.1% final PPh 22 (Bappebti-registered) | 0.21% final PPh 22, withheld by the licensed domestic trader (PAKD) |
| Selling crypto, other/foreign platform | 0.2% final PPh 22 | 1% final PPh 22, collected by an appointed foreign platform or self-paid |
| Buying crypto | VAT of 0.11% or 0.22% | No VAT (crypto treated like securities) |
| Mining income | 0.1% final PPh | General income tax rates from tax year 2026 |
The VAT change follows crypto’s new status. Oversight passed from the commodities regulator Bappebti to the Financial Services Authority (OJK) on 10 January 2025, and crypto is now treated as a financial asset similar to securities, which Indonesian VAT law exempts.
Who Pays the Tax and How It Is Collected
The tax falls on the seller. Under PMK 50/2025, a seller is anyone who sells or swaps crypto. The rate is applied to the transaction value, not to your profit. Because it is a final tax on gross value, it is due whether a particular sale makes a gain or a loss.
On a domestic licensed exchange (0.21%)
If you trade on a Pedagang Aset Keuangan Digital (PAKD), a crypto trader licensed by OJK, the platform collects, pays and reports the 0.21% PPh 22 for you (Article 12). It must also issue a withholding slip (bukti potong) by the end of the tax month.
The regulation defines “transaction value” for three cases:
- Crypto sold for rupiah or other fiat: the money paid by the buyer. Foreign currency is converted at the Finance Minister’s exchange rate.
- Crypto-to-crypto swaps: the rupiah value of each crypto asset handed over, so swaps are taxable too.
- Other crypto transactions: the payment the seller receives.
On a foreign exchange (1%)
PMK 50/2025 lets the government appoint a foreign platform as a tax collector (Articles 17 to 18). The DJP can do this when the platform passes thresholds for transaction value or user traffic from Indonesia over 12 months, or when the platform asks to be appointed. A platform counts Indonesian users by address, payment method, Indonesian IP address or +62 phone number, or “Indonesia” picked as the country at sign-up (Article 19).
There are then two situations:
- The foreign exchange has been appointed. It collects the 1% final PPh 22 from your sales. If it fails to, the 1% is still owed and you must pay and report it yourself (Article 21).
- The foreign exchange has not been appointed. You are still taxed at 1%, and you must self-pay and report it through the monthly unified income-tax return, the SPT Masa PPh Unifikasi (Article 22). Missing this can lead to penalties under the general tax procedures law.
One more detail: income tax charged on the same transaction by another country cannot be credited against this Indonesian 1% tax (Article 20(3)).
A DJP official told ANTARA that foreign exchanges would be appointed by Director General decree and that the higher 1% rate, proposed by OJK, aims to steer users toward domestic exchanges. We could not find a public list of appointed foreign platforms, so check with your platform or the DJP before assuming tax is being withheld for you.
Illustrative Example: Same Trade, Different Platform
The figures below are illustrative only and use the rates in PMK 50/2025. They ignore trading fees, VAT on platform fees and price movements.
Suppose an Indonesian resident sells crypto worth Rp100,000,000:
| Domestic licensed exchange | Foreign exchange | |
|---|---|---|
| Rate (final PPh 22) | 0.21% | 1% |
| Tax on Rp100,000,000 | Rp210,000 | Rp1,000,000 |
| Who handles it | Exchange withholds and reports | Appointed platform collects, or you self-pay and report |
The gap is Rp790,000 on a single Rp100 million sale. Since the tax is charged on every sale and every swap, it adds up quickly for active traders. Ten Rp10 million swaps a month on a foreign exchange would mean Rp1,000,000 in tax for that month (10 × Rp10,000,000 × 1%), against Rp210,000 at the domestic rate. If you’re weighing one large purchase against steady small ones, see our guide to DCA vs lump-sum investing. Buying isn’t taxed, but each later sale or swap is.
Fees Still Carry VAT
Crypto itself is VAT-exempt, but the platform’s service is not. Article 5 of PMK 50/2025 charges VAT at 12% on a base of 11/12 of the platform’s commission or fee, an effective 11% of the fee. The fee covers trading, deposit, withdrawal, transfer and wallet services. So the “no VAT for buyers” headline means no VAT on the crypto you buy, not on the fees.
Mining, Staking and Other Income
- Mining: From tax year 2026, block rewards, transaction fees and related mining income are taxed at general income tax rates and reported in the annual return (Articles 24, 25 and 27), replacing the old 0.1% final tax. Mining services also carry VAT at an effective 2.2%. Selling mined coins on a platform falls under the normal 0.21% rule (Article 26).
- Staking, airdrops and DeFi: PMK 50/2025 does not name staking rewards or airdrops directly. Don’t assume they are tax-free; ask the DJP or a registered tax consultant (konsultan pajak).
Reporting: Annual Return and New Data Sharing
The same DJP article notes that crypto holdings can be listed as assets in your annual tax return (SPT Tahunan). Record the year and cost of acquisition. Holding crypto is not itself taxed as income.
Transparency is also growing. Under the OECD’s Crypto-Asset Reporting Framework (CARF), Indonesian crypto service providers have had to collect self-certifications from users since 1 January 2026. The first reports, covering 2026 data, are due in 2027 (DJP CARF guide; PMK 108/2025 summary). They cover crypto-to-fiat trades, swaps, transfers (including known staking and mining income) and retail payments above US$50,000, and CARF data is exchanged between countries. Using a foreign exchange is unlikely to keep trades out of view.
Possible Changes Ahead
On 16 October 2026, OJK commissioner Adi Budiarso said OJK had proposed lowering the 0.21% rate to 0.1%, in line with the final tax on stock sales. DJP Director General Bimo Wijayanto said a cut could make sense but that lost revenue would have to be weighed (Ortax, 20 Oct 2026). This is only a proposal. The 0.21% and 1% rates in PMK 50/2025 apply until a new regulation is published.
Practical Checklist for Indonesian Traders
- Check whether your platform is a licensed PAKD. OJK supervises licensed crypto traders. Platform risk matters too, so read our overview of exchange risks and Binance security concerns.
- Keep records of every sale and swap, including the rupiah value and date, plus the withholding slips your exchange issues.
- On a foreign exchange, find out whether it has been appointed to collect the 1%. If not, plan to self-pay and file the monthly SPT Masa PPh Unifikasi.
- If you withdraw to your own wallet, secure your keys first with our crypto security guide.
- Confirm your situation with the DJP (pajak.go.id) or a registered tax consultant, especially for mining, staking or business-scale trading.
FAQ
Is crypto profit taxed in Indonesia?
Trading on platforms is taxed through a final 0.21% (domestic) or 1% (foreign) PPh 22 on the transaction value, not through a separate capital-gains tax on profit. Mining income is taxed at general rates from tax year 2026.
Do I pay tax when I buy crypto?
No VAT is charged on the crypto itself since 1 August 2025. Platform fees still carry VAT, and the income tax applies when you sell or swap.
Is swapping one coin for another taxable?
Yes. PMK 50/2025 treats crypto-to-crypto swaps made through a platform as taxable transactions, valued at the rupiah value of the crypto handed over.
What if my foreign exchange doesn’t withhold the tax?
If the platform hasn’t been appointed as a collector, or fails to collect, the 1% final PPh 22 is still due. You must pay it yourself and report it in the SPT Masa PPh Unifikasi.
Who supervises crypto exchanges in Indonesia now?
OJK, since 10 January 2025, taking over from Bappebti.
Disclaimer: This article is a general educational explainer based on regulations and official publications checked in November 2026. It is not tax, legal or financial advice. Tax rules can change and individual circumstances differ, so confirm your obligations with the Directorate General of Taxes (DJP) or a registered tax consultant before acting.
Sources
- PMK 50/2025 full text — DJP regulation database
- PMK 50/2025 — JDIH Kemenkeu record
- DJP press release, 31 July 2025
- DJP article: crypto tax then and now
- OJK joint press release on the Bappebti-to-OJK transfer, 10 Jan 2025
- ANTARA: DJP to appoint foreign platforms to collect PPh 22
- DJP CARF implementation guide
- PMK 108/2025 summary — JDIH Kemenkeu
- Ortax: OJK proposes cutting crypto PPh to 0.1% (20 Oct 2026)
- CNBC Indonesia: Kemenkeu says crypto remains a tax object (16 Oct 2026)