
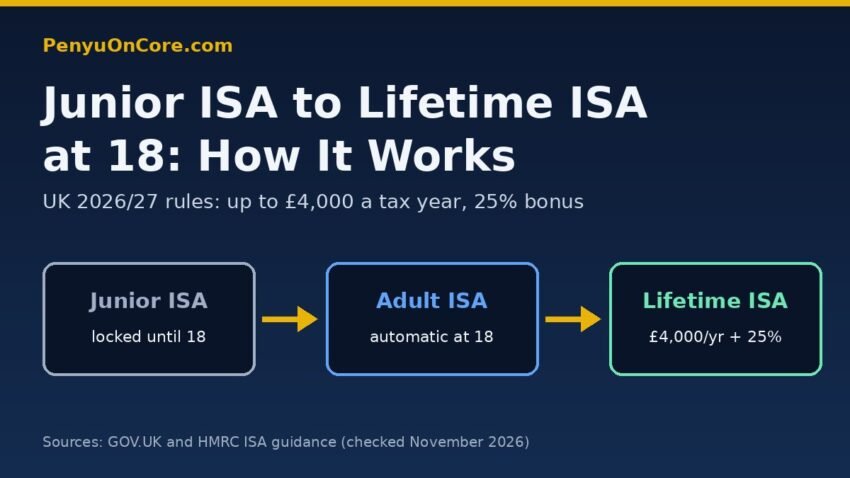
Short answer: You can’t move a Junior ISA to Lifetime ISA directly while it is still a Junior ISA. A Junior ISA can only be transferred to another Junior ISA. But on the 18th birthday it automatically becomes an adult ISA, and from then you can move up to £4,000 per tax year from it into a Lifetime ISA by ISA transfer and get the 25% government bonus on that amount. Anything above £4,000 can stay in an ordinary ISA (or be withdrawn), and more can move across in a later tax year.
Below: the 2026/27 UK rules, the transfer steps, the £20,000 allowance question and the Lifetime ISA catches.
Why a Junior ISA can’t go straight into a Lifetime ISA
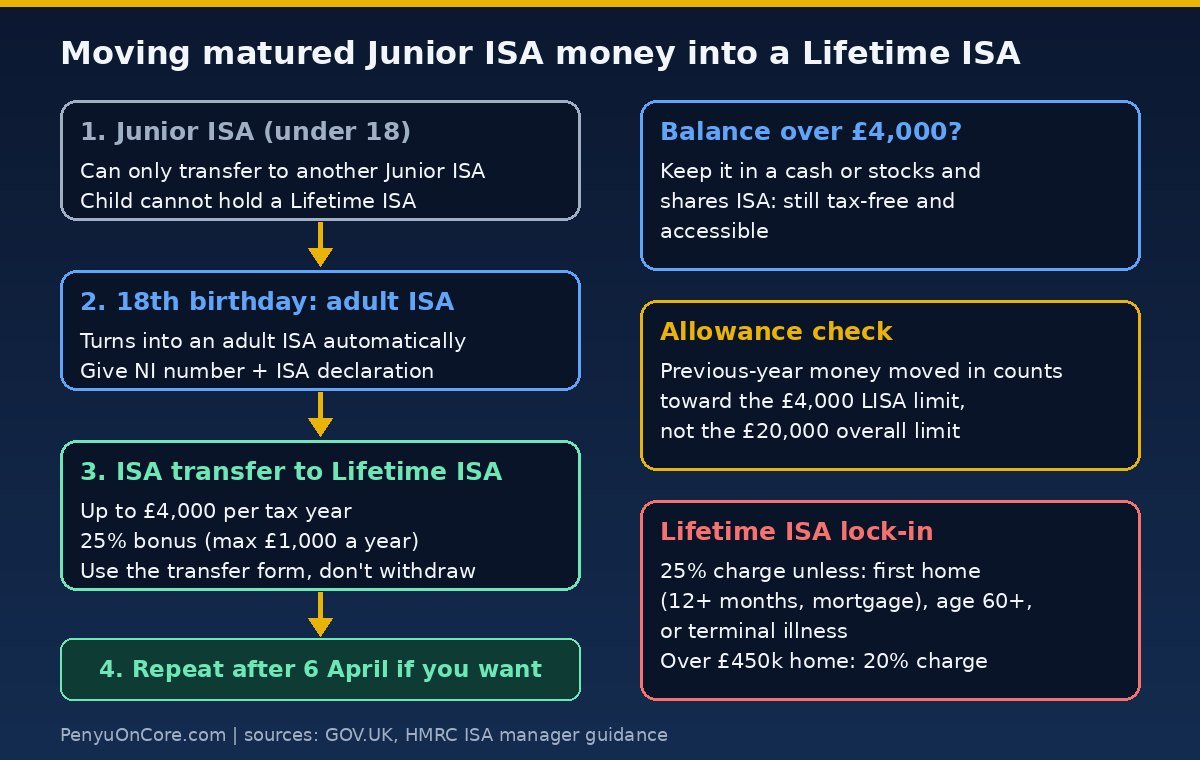
GOV.UK is blunt about it: you can move money between a child’s Junior ISAs, or from a Child Trust Fund into a Junior ISA, but “you cannot transfer money between a Junior ISA and an adult ISA” (GOV.UK: Junior ISA – add money). A child can’t hold a Lifetime ISA anyway. HMRC’s guidance for providers says a child “cannot hold an innovative finance ISA or a Lifetime ISA” (HMRC: Junior ISAs for ISA managers).
The route opens on the 18th birthday. HMRC tells ISA providers that someone can apply for a Lifetime ISA in the tax year they turn 18, but “can only transfer funds from a matured Child Trust Fund (CTF) or Junior ISA into an ISA or Lifetime ISA on or after their 18th birthday” (HMRC: information you need from investors).
What happens to a Junior ISA at 18
- It turns into an adult ISA automatically. GOV.UK says Junior ISAs “automatically turn into an adult ISA when the child turns 18”, and the young person can then take money out (GOV.UK: manage a Junior ISA).
- The tax-free status carries on. HMRC says investments held at 18 keep their tax advantages. The provider can’t accept new payments into that former Junior ISA until the account holder gives their National Insurance number (if they have one) and makes the adult ISA declaration, including that they live in the UK (HMRC: Junior ISA closure and the 18th birthday).
- Some providers move the money for you. For example, NS&I says that on the child’s 18th birthday it automatically transfers the money into an NS&I adult cash ISA, and it contacts the person managing the account about a month beforehand (NS&I Junior ISA).
From that point the money is in a cash ISA or a stocks and shares ISA. HMRC’s transfer rules let funds in cash ISAs, stocks and shares ISAs and cash held in Innovative Finance ISAs be transferred to a Lifetime ISA, as long as “the amount transferred must not exceed the annual Lifetime ISA subscription limit” (HMRC: transfer an ISA).
The Lifetime ISA rules that matter here
According to GOV.UK’s Lifetime ISA guide:
- You must be 18 or over but under 40 to open one, and UK resident (with exceptions for armed forces and Crown servants).
- You can put in up to £4,000 each tax year until you turn 50. The government adds a 25% bonus, up to £1,000 a year.
- The £4,000 counts towards the overall ISA limit, which is £20,000 for 2026/27.
- It can hold cash, stocks and shares, or both.
Does the transfer use up the £20,000 allowance?
Usually not, but it depends on which tax year the money was paid in. HMRC’s Lifetime ISA guidance says previous-year payments moved from another ISA into a Lifetime ISA count towards the £4,000 Lifetime ISA limit “but not the overall ISA payment limit for the tax year.” If the transfer includes current-year payments, those must be transferred in full and do count towards the overall limit (HMRC: transfer Lifetime ISAs). A matured Junior ISA balance is not new adult money. If Junior ISA payments were made earlier in the same tax year as the 18th birthday, ask the provider how they will be treated before you transfer.
How to move matured Junior ISA money into a Lifetime ISA
- Wait until the 18th birthday. You can open the Lifetime ISA in the tax year you turn 18, but the money can only move on or after the birthday.
- Give the current provider your adult details if they ask. That means your National Insurance number and the adult ISA declaration.
- Open a Lifetime ISA with a provider that accepts transfers in. Not all of them do. HMRC says ISA managers are “not obliged to accept transfers-in”. Check that the provider takes transfers from a cash or stocks and shares ISA.
- Ask the new Lifetime ISA provider to start a transfer of up to £4,000. Do this through their ISA transfer form. Don’t withdraw the cash and pay it back in yourself. GOV.UK warns that if you withdraw instead of transferring, you can’t reinvest that part of your allowance (GOV.UK: transferring your ISA). For a Lifetime ISA, a pay-in also counts as a new payment against the £20,000.
- Allow time. GOV.UK says transfers should take no longer than 15 working days between cash ISAs and 30 calendar days for other types.
- Repeat next tax year if you want. The £4,000 limit resets every 6 April, so a bigger balance can be moved in yearly chunks. That works only if you don’t make other Lifetime ISA payments that year.
Watch the provider’s own rules. Practical details vary. OneFamily, for instance, says that if you move matured Junior ISA money into its Lifetime ISA or Stocks and Shares ISA, you can’t leave any money in the matured Junior ISA. You transfer the rest to another ISA or withdraw it, and the account is closed (OneFamily). AJ Bell says a Lifetime ISA opened with it must be funded in the same tax year or it will be closed (AJ Bell). If you’re moving a balance bigger than £4,000, it’s simplest to transfer the extra into a normal stocks and shares or cash ISA in the same go. Our guide to holding two stocks and shares ISAs in one tax year explains how multiple ISAs work now.
Worked example (illustrative, no growth assumed)
Say a matured Junior ISA holds £10,000 and the new adult moves £4,000 into a Lifetime ISA by transfer:
| Item | Amount | Rule |
|---|---|---|
| Moved to Lifetime ISA | £4,000 | Annual Lifetime ISA limit |
| Government bonus | £1,000 | 25%, max £1,000 a year |
| Left in adult ISA | £6,000 | Still tax-free, accessible |
| Next tax year | Up to £4,000 more | Limit resets 6 April |
Before you do it: the Lifetime ISA catches
The 25% bonus is generous, but the money is locked in. GOV.UK says you can withdraw without a charge only to buy your first home, from age 60, or if you’re terminally ill with less than 12 months to live. Any other withdrawal costs 25%. On a pot of £800 plus a £200 bonus, that leaves you with £750, less than you put in (GOV.UK: withdrawing from a Lifetime ISA).
- First-home rules: you must buy at least 12 months after your first payment into the Lifetime ISA, use a conveyancer or solicitor, and buy with a mortgage. For homes over £450,000 the charge is now 20% rather than 25%. HM Treasury introduced that from 29 October 2026 (HM Treasury government response).
- Money you may need soon (university costs, a car, a buffer) is usually better kept accessible. See how much emergency fund you need.
- The Lifetime ISA is being replaced for new savers. The government will introduce a First Time Buyer ISA from April 2029, offered in place of the Lifetime ISA. LISAs opened before then can carry on under existing terms, but you won’t be able to transfer a LISA into the new product. You will be able to use both towards the same purchase (same HM Treasury source). At 18, opening a LISA now is still possible. It’s also an argument for not waiting if you want one.
If the young person also holds Premium Bonds bought for them as a child, the control rules change at a different age. See what happens to Premium Bonds when a child turns 16.
FAQ
Can parents open the Lifetime ISA for their child before 18?
No. You must be 18 or over to open a Lifetime ISA, and children can’t hold one.
Can I move the whole Junior ISA into a Lifetime ISA at once?
Only up to £4,000 in a tax year. The rest can stay in, or move to, a cash or stocks and shares ISA.
Does the government bonus count towards the £4,000?
No. Hargreaves Lansdown’s Lifetime ISA FAQ says the bonus doesn’t count towards the £20,000 overall limit or the £4,000 Lifetime ISA limit (HL FAQ).
What about a Child Trust Fund?
A matured Child Trust Fund follows the same timing rule. HMRC says funds can be moved into an ISA or Lifetime ISA on or after the 18th birthday, and a transfer of cash from a matured CTF counts as a Lifetime ISA payment (HMRC: managing Lifetime ISA accounts).
Disclaimer: This article is general information about UK ISA rules as published by GOV.UK and HMRC as of November 2026. It is not financial or tax advice. Rules and provider terms can change, and investments can fall as well as rise. Check with your provider or a regulated adviser before acting.