
ISA transfer taking too long? Check which deadline applies first. GOV.UK says a transfer between two cash ISAs should take no longer than 15 working days, and any other ISA transfer no longer than 30 calendar days. Once that time has passed, chase the provider you are moving to. If you don’t get a fair answer, make a formal complaint, and after that you can go to the free Financial Ombudsman Service.
This guide covers when the clock actually starts, where transfers usually get stuck, and the steps to take if yours is overdue. Everything was checked against GOV.UK, HMRC, FCA and Financial Ombudsman Service pages in November 2026. The rules can change, so check the linked pages before you act.
ISA transfer taking too long? The official time limits
The consumer page GOV.UK: Transferring your ISA sets out two limits:
| Type of transfer | Should take no longer than | Notes |
|---|---|---|
| Cash ISA to cash ISA | 15 working days | HMRC splits this into fixed stages (see below) |
| Any other transfer (e.g. stocks and shares ISA, cash to stocks and shares) | 30 calendar days | Done under the providers’ ISA terms and conditions |
| Investments held in an innovative finance ISA | No fixed limit stated | GOV.UK says to ask your provider how long it will take |
Note the units. Cash-to-cash transfers are counted in working days, so weekends and bank holidays don’t count. Everything else is counted in calendar days.
When does the 15-day clock start?
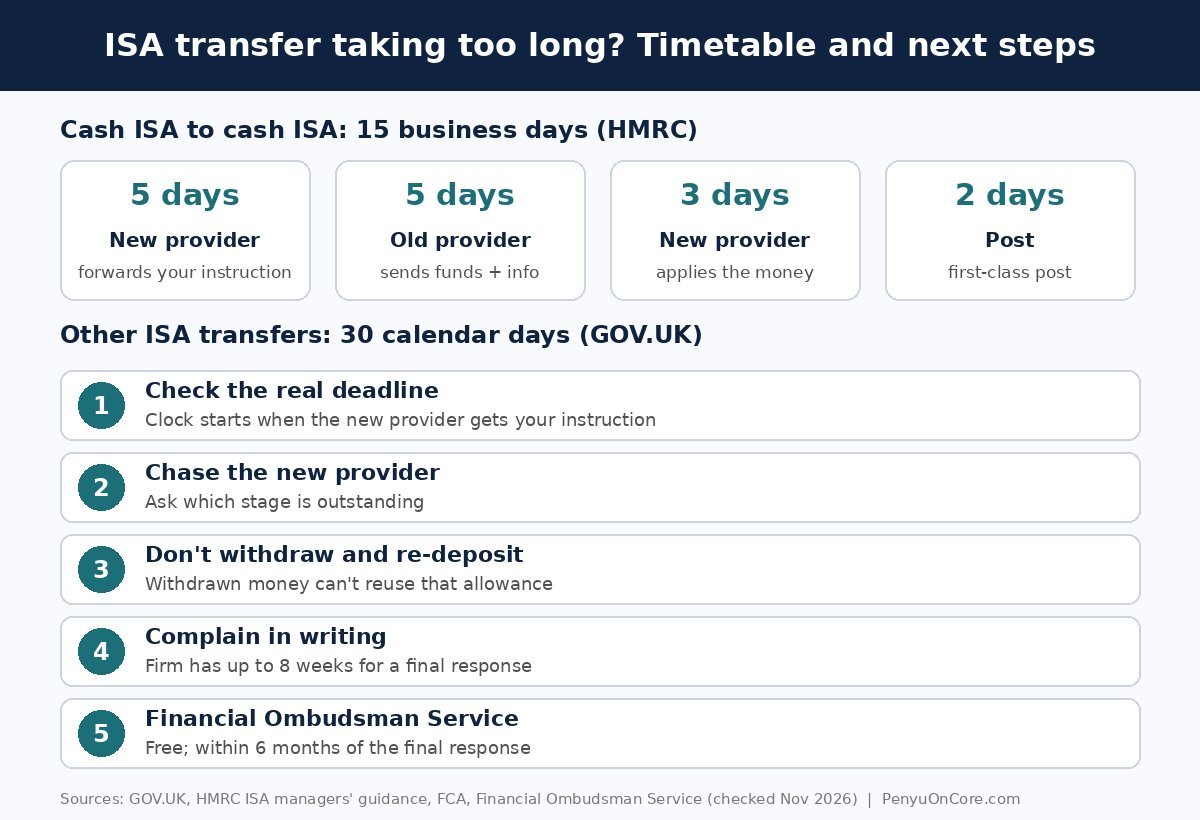
HMRC’s guidance for providers, Transfer an ISA if you’re an ISA manager, says cash ISA to cash ISA transfers must take place within 15 business days of the new ISA manager receiving the transfer instruction. The day you filled in the form doesn’t count. If you asked for the transfer to start on a later date, the 15 days start from that date instead. HMRC breaks the 15 days down like this:
- The new provider has 5 business days to forward your instruction to the old provider.
- The old provider has 5 business days to send the funds and the account information.
- The new provider has 3 business days to apply the money to your new ISA.
- The other 2 days allow for first-class post between the two firms.
HMRC says this timetable does not apply when you move cash ISA money into a stocks and shares, innovative finance or Lifetime ISA, or the other way round. Those transfers are completed under the providers’ terms and conditions, within the 30 calendar days that GOV.UK gives for “other types of transfer”.
Common reasons an ISA transfer is delayed
A late transfer usually means one step in the handover between the two firms has stalled. The money hasn’t disappeared. These are the usual causes, based on how HMRC describes the process:
1. A fixed-rate or notice ISA
Moving out of a fixed-term or notice account before it ends can mean an exit or interest penalty. HMRC says the old provider can contact you and take a revised instruction to transfer once the notice period ends or the product matures. That revised instruction is treated as a new transfer instruction that starts a fresh timetable. So a transfer that looks “late” may have been reset deliberately to avoid a penalty. Ask whether that has happened.
2. Moving shares “in specie”
For stocks and shares ISAs, HMRC says the old provider can move the investments themselves, cash, or both, subject to both providers’ terms. If the holdings move as they are, the new provider has to re-register them. That takes longer than a cash transfer, and some funds or shares may not be held on the new platform at all. If your old provider sells the holdings and sends cash instead, you will be out of the market for a while.
3. Paperwork and matching problems
The old provider must send the new one a transfer history form with your details, such as your name, permanent address, date of birth and National Insurance number. If those don’t match the old provider’s records, or the old provider’s terms require your signature on the transfer authority, things can stall until the problem is fixed. HMRC lets providers send this information electronically. If the old provider doesn’t send the history form with the money, HMRC says it must tell the new provider the ISA type and amount, then send the form within 30 calendar days of the transfer.
4. The new provider won’t take it
HMRC says ISA managers are not obliged to accept transfers in. Check that the new account accepts transfers, and whether it takes current-year money, previous years’ money or both, before you assume the old provider is to blame. Our guide to paying into two stocks and shares ISAs in the same tax year explains how current-year subscriptions work.
What to do if your ISA transfer is overdue
- Work out the real deadline. For cash to cash, count 15 working days from the date the new provider received your instruction. For anything else, count 30 calendar days.
- Contact the new provider first. GOV.UK says to contact your ISA provider if a transfer takes longer than it should. You applied to the new provider, so it can see which stage the transfer has reached. Ask which of the steps above is outstanding.
- Don’t withdraw and re-deposit. GOV.UK warns that if you withdraw money instead of using the transfer process, you can’t reinvest that part of your tax-free allowance again. HMRC adds that money paid to you rather than directly to the new provider is treated as a withdrawal. Don’t cancel and cash out out of frustration.
- Make a formal complaint in writing. The FCA’s guide to complaining says to tell the firm what happened and when, ask it to put things right, and keep a record of your contact. If you think you lost interest or growth because of the delay, say so and explain how you worked it out.
- Wait for the final response, up to 8 weeks. The FCA says firms must acknowledge a complaint in writing unless they resolve it within 3 business days, and in general must give you the outcome in writing within 8 weeks.
- Go to the Financial Ombudsman Service. If you’re unhappy with the final response, or 8 weeks pass without one, the Financial Ombudsman Service says you can bring the complaint to it free of charge. You need to do this within 6 months of the date on the final response.
If both firms blame each other, complain to both. HMRC splits the work between the old and new provider, so each one can be responsible for its own stage.
Special cases: Lifetime ISA and Junior ISA transfers
GOV.UK says there are extra restrictions on transferring a Lifetime ISA or Junior ISA. HMRC’s guidance says moving Lifetime ISA money into a cash, stocks and shares or innovative finance ISA is treated as a withdrawal and may be liable to the withdrawal charge. Moving it to another Lifetime ISA does not trigger the charge. If you are moving a Lifetime ISA, see our step-by-step guide on transferring a Lifetime ISA to another provider. If you are moving money from a Junior ISA, read moving a Junior ISA into a Lifetime ISA.
FAQ
Does a delayed transfer use up my ISA allowance?
No, as long as it goes through as a proper transfer. HMRC says transferred investments and cash are not new subscriptions for the overall subscription limit, and the tax benefits are preserved.
Who should I chase, the old or the new provider?
Start with the new provider. GOV.UK’s process has you apply to the provider you are moving to, and that provider asks the old one to release the money. If the new provider confirms the request was sent on time, chase the old provider as well.
Is 30 days the limit for a stocks and shares ISA transfer?
GOV.UK says transfers other than cash to cash should take no longer than 30 calendar days. For investments inside an innovative finance ISA, GOV.UK gives no fixed limit and says to ask your provider.
Can I get compensation for lost interest?
You can ask for it in your complaint. Whether you get anything depends on the facts. If the firm’s final response doesn’t satisfy you, the Financial Ombudsman Service can look at the complaint independently.
Disclaimer: This article is general information, not financial, tax or legal advice. ISA rules and provider terms can change, so check GOV.UK, HMRC and your providers’ terms, or speak to a qualified adviser, before you make decisions about your savings.