
You can transfer a Lifetime ISA to another provider at any time without the 25% withdrawal charge, as long as it goes directly into another Lifetime ISA and you start the switch through the new provider. HMRC says the transfer must be completed within 30 calendar days of your request. Your bonus and your 12-month first-home clock both move with the account.
Switching your Lifetime ISA (LISA) can get you a better rate, lower fees or more fund choice. But LISA rules are stricter than other ISAs, and a wrongly made switch can cost you a quarter of the money you move. This guide covers the 2026/27 tax year rules, using HMRC and GOV.UK guidance checked in November 2026.
The Short Version: LISA Transfer Rules at a Glance
| Rule | What it means for you |
|---|---|
| LISA to LISA | No withdrawal charge and no limit on the amount |
| Deadline | Within 30 calendar days of the transfer request |
| This tax year’s payments | Must be moved in full, not split |
| £4,000 allowance | A LISA-to-LISA transfer does not use it up |
| Government bonus | Goes with the account, including any bonus still pending |
| 12-month home rule | Counts from your first payment into the original LISA |
| LISA to another ISA type | Treated as a withdrawal: 25% charge unless you’re 60+ or terminally ill |
Can You Transfer a Lifetime ISA Without Losing the Bonus?
Yes. HMRC’s guidance on transferring Lifetime ISAs between managers says you can move a LISA from one provider to another without a withdrawal charge, and there is no limit on how much you transfer. Your existing bonus stays in the pot because it moves along with your savings.
Your money has to go directly from the old provider to the new one. Never take the money out yourself and pay it into a new account. HMRC’s ISA manager transfer rules say that if funds are paid to the investor instead of the new manager, it counts as a withdrawal. The money loses its tax-free wrapper, and with a LISA there may also be a withdrawal charge. In most cases that charge is 25%, which wipes out the bonus and also eats into your own money.
What about a bonus that hasn’t arrived yet?
Providers claim the 25% bonus from HMRC in monthly claim periods running from the 6th of one month to the 5th of the next, according to HMRC’s guidance on managing Lifetime ISA accounts. A recent payment may therefore still have its bonus “in flight” when you switch. HMRC’s transfer guidance covers both cases:
- The new provider can claim any bonus that is still outstanding.
- If the old provider has already claimed a bonus that arrives after the transfer, it must pass that bonus on to the new provider.
Mechanics vary: Plum’s help centre says the old or new provider makes the claim depending on whether the transfer completes before or after the 5th. Either way, you shouldn’t lose a bonus you’re entitled to. It may just show up a few weeks later than you expect.
How to Transfer a Lifetime ISA, Step by Step
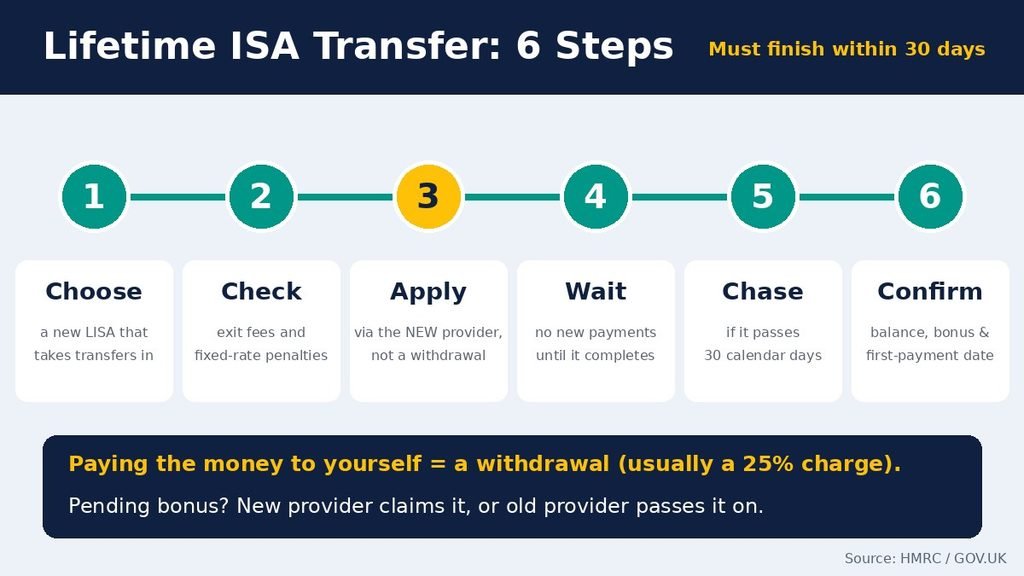
- Pick a new provider that accepts LISA transfers in. Providers don’t have to accept transfers, so check first. Look at the rate, fees, fund range, and whether the account is cash or stocks and shares.
- Check exit terms with your current provider. GOV.UK’s ISA transfer page warns that providers may have their own restrictions or charges. Fixed-rate cash LISAs, for example, can carry early-exit penalties.
- Open the new LISA and request the transfer through the new provider. You fill in its transfer form, usually online. The new provider then contacts your old one. Don’t close the old account yourself.
- Hold off on new payments. Some providers ask you to wait until the transfer completes before paying in. Tembo, for example, says that paying into its new LISA before the transfer finishes resets the account’s opening date.
- Track the 30-day deadline. If things drag on past 30 calendar days, chase both providers. GOV.UK says to contact your ISA provider if a transfer takes longer than it should.
- Check the final balance. Once it completes, make sure your transferred balance, any pending bonus and your original first-payment date all appear on the new account.
How Long Does a Lifetime ISA Transfer Take?
According to HMRC, a LISA-to-LISA transfer must be done within 30 calendar days of receiving your transfer request. The 15-working-day deadline you may have seen elsewhere only applies to transfers between cash ISAs. GOV.UK sets 30 calendar days for other types of transfer, and that includes LISAs.
Investments are often sold to cash for the transfer, so a stocks and shares LISA may be out of the market for a while. Ask whether your holdings can move “in specie” (without selling).
Does the Transfer Reset the 12-Month First-Home Rule?
No. You can usually only use a LISA for a first home without a charge if you withdraw at least 12 months after your first payment into it (see HMRC’s first-time purchase rules). HMRC’s digital reporting guidance for LISA providers says that when a transfer is done correctly, you can withdraw for a property purchase 12 months after you first paid into your original LISA. Your eligibility date moves to the new provider with you.
The catch is step 4 above. If you pay into the new account before the transfer finishes, or merge the transfer into a LISA you already hold, the provider may use a different date. Ask the new provider to confirm in writing if you’re buying soon. One more point for buyers: from 29 October 2026, the charge for using a LISA on a home costing more than £450,000 dropped from 25% to 20%.
The £4,000 Limit and This Tax Year’s Payments
Moving cash or investments from one LISA to another is not a new payment, so it doesn’t count towards the £4,000 Lifetime ISA limit or the overall ISA allowance (£20,000 for 2026/27 according to GOV.UK). HMRC lists “cash or investments transferred between 2 Lifetime ISA accounts” among the things that are not current-year payments.
Two related rules matter:
- Current-year payments must move in full. If you’ve paid in since 6 April 2026, you can’t leave part of this year’s money behind.
- You can only pay into one LISA per tax year. HMRC says you can hold more than one LISA over your lifetime but can generally only pay into one each tax year. If you’ve paid into your old LISA this year and want to pay into a new one, move this year’s payments across too. Other ISA types now work differently, as our guide to two stocks and shares ISAs in the same tax year explains.
Transfers into a LISA from other accounts work differently. Money from a cash or stocks and shares ISA, or from a Help to Buy ISA, does count towards the £4,000 limit. We cover these routes in Junior ISA to Lifetime ISA and Child Trust Fund to Lifetime ISA.
Transferring a LISA to a Different Type of ISA
You can move a LISA into a cash ISA or a stocks and shares ISA, but HMRC treats it as a withdrawal. The 25% charge applies unless the transfer happens after your 60th birthday or you have declared a terminal illness. The receiving provider must tell your old provider that the new account is not a LISA, so the charge can’t be skipped by accident. GOV.UK also says that moving LISA money into a Help to Buy ISA triggers the 25% charge.
Can You Still Transfer After 40 or 50?
Yes. You can’t open a LISA for new savings once you’re 40, but HMRC lets someone aged 40 or over open a LISA specifically to receive a transfer from a LISA they opened before turning 40. At 50 you can no longer pay in, but the account stays open and can still be moved to a cheaper or better provider. Our Lifetime ISA at 50 guide explains what changes at that age.
Will the New First Time Buyer ISA Affect Transfers?
In its October 2026 consultation response, the government confirmed a new First Time Buyer ISA from April 2029. It will replace the LISA for new savers, and existing LISAs can carry on under their current terms. The design summary says transfers between the new product and LISAs will not be allowed, though both can be used for the same purchase. None of this changes LISA-to-LISA transfers today.
FAQ
Do I lose my bonus if I transfer my Lifetime ISA?
No. A LISA-to-LISA transfer keeps all bonus already paid, and HMRC says any outstanding bonus can be claimed by the new provider or passed on by the old one.
Can I transfer only part of my Lifetime ISA?
Yes for money from previous tax years, subject to what your providers allow. Payments from the current tax year must be moved in full.
Is there a fee to transfer a Lifetime ISA?
The government doesn’t charge one, but providers can set their own exit fees or penalties (for example on fixed-rate accounts). Check your terms before you start.
Can I transfer my Lifetime ISA to my partner?
No. A LISA belongs to one person. Moving money to someone else means taking a withdrawal, which normally carries the 25% charge.
This article is for general information only and is not financial advice. ISA rules can change, so check GOV.UK and your provider’s terms, or speak to a regulated financial adviser, before making decisions about your savings.